

IEC | INDONESIA EXPORT CENTER
Your Global Sourcing Partner
Evaluating Greenhouse Gas Claims for Palm Fatty Acid Distillate
Palm Fatty Acid Distillate is used or evaluated as a feedstock in several industrial supply chains, including selected oleochemical and biofuel-related applications.
As companies develop greenhouse gas inventories and sustainability reporting programs, questions may arise concerning PFAD’s lifecycle emissions, feedstock classification, allocation of upstream impacts, and eligibility for particular regulatory schemes.
These questions cannot be answered reliably by assuming that all PFAD has the same carbon footprint.
A defensible carbon accounting assessment requires a clearly defined methodology, system boundary, relevant activity data, appropriate emission factors, and documented assumptions.
Indonesia Export Center (IEC) facilitates potential Indonesian PFAD supplier inquiries but does not certify lifecycle emissions, provide audited carbon footprints, or guarantee regulatory feedstock eligibility.
What Is Carbon Accounting?
Carbon accounting involves measuring or estimating greenhouse gas emissions associated with an activity, organization, product, or supply chain.
For a material such as PFAD, different accounting exercises may produce different results because they use different boundaries and methods.
For example:
- A company greenhouse gas inventory.
- A product carbon footprint.
- A cradle-to-gate lifecycle assessment.
- A cradle-to-grave lifecycle assessment.
- A regulatory biofuel greenhouse gas calculation.
These should not be treated as interchangeable.
What Is a Lifecycle Assessment?
A lifecycle assessment (LCA) examines environmental impacts across a defined product system.
For PFAD, a lifecycle assessment may consider relevant stages such as:
- Upstream palm feedstock production.
- Transport to processing facilities.
- Palm oil processing.
- Refining operations.
- PFAD generation and collection.
- Storage.
- Packaging.
- Transportation.
- Industrial conversion.
- End-of-life or downstream stages, where included.
The stages actually included depend on the assessment’s scope.
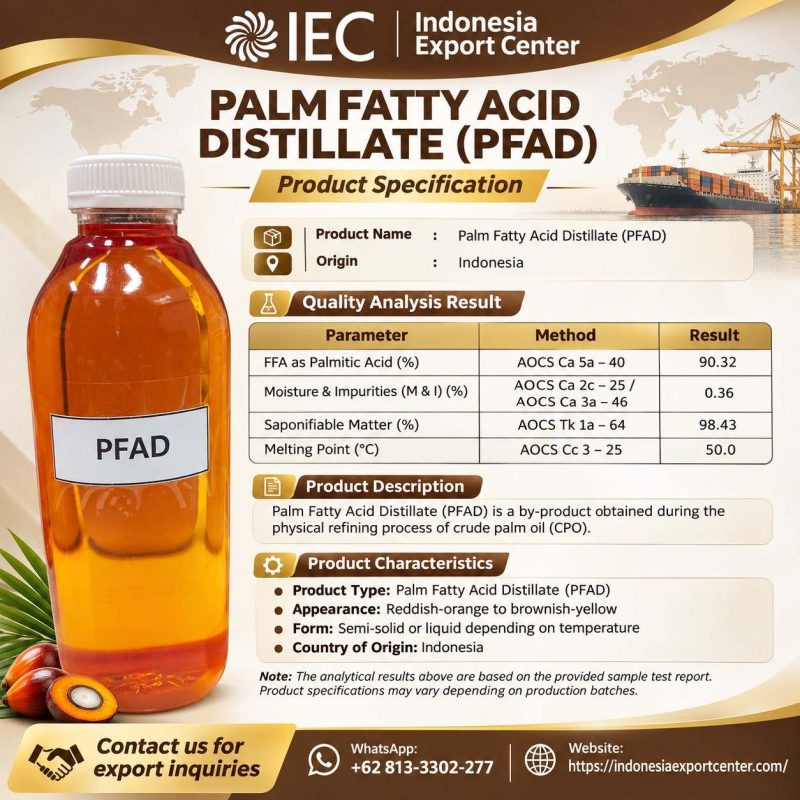
IEC PFAD Reference Specifications
| Parameter | Reference |
|---|---|
| FFA, as Palmitic | Minimum 90% |
| Moisture & Impurities | Maximum 1.0% |
| Iodine Value | Maximum 50 |
| Melting Point | 36–46°C |
| Gardner Colour | Maximum 7 |
| Appearance | White / Off White Solid |
These are product-quality references.
They do not establish greenhouse gas emissions, lifecycle savings, or environmental certification.
Defining the Functional Unit
An LCA must identify the quantity or function against which results are calculated.
Depending on the assessment, a functional unit may be based on:
- A defined mass of PFAD.
- A defined quantity of converted product.
- A defined energy output.
- Another appropriate product-system function.
Comparisons must use consistent and justified units.
Defining the System Boundary
Cradle-to-Gate
May include relevant upstream production, processing, and activities up to a specified facility gate.
Gate-to-Gate
Examines a defined processing stage.
Cradle-to-Grave
Includes a broader lifecycle, potentially extending to use and end-of-life stages.
A result from one boundary cannot automatically be compared with a result from another.
The Importance of Allocation
PFAD is generated alongside other products during palm oil refining.
Lifecycle accounting must address how relevant environmental burdens are attributed among products and co-products.
Possible approaches under different methodologies may include:
- Mass-based allocation.
- Economic allocation.
- Energy-based allocation.
- System expansion or substitution approaches.
- Other method-specific treatments.
The selected method can materially influence the result.
It must be justified under the applicable standard or regulatory framework.
Why By-Product Status Does Not Mean Zero Emissions
PFAD’s commercial description as a by-product does not automatically establish zero upstream emissions.
The treatment of co-products, residues, and wastes differs across accounting frameworks.
A claim of zero emissions or a fixed percentage reduction requires a specific, defensible basis.
IEC does not publish an unsupported universal PFAD carbon value.
Data Needed for a PFAD Carbon Assessment
| Data Category | Examples |
|---|---|
| Product Identity | PFAD grade and composition |
| Refinery Information | Relevant production facility |
| Feedstock Information | Available upstream records |
| Energy Use | Relevant processing energy |
| Transportation | Mode, route, distance |
| Storage | Relevant energy and handling |
| Allocation | Method and justification |
| Emission Factors | Documented sources |
| Functional Unit | Defined quantity or function |
| System Boundary | Included lifecycle stages |
| Verification | Applicable independent review |
The necessary data depend on the assessment methodology.
Supplier Data vs Modelled Data
A carbon assessment may use primary supplier data, secondary datasets, or a combination.
Buyers should distinguish:
Primary Data: Information collected from relevant actual operations.
Secondary Data: Published datasets, industry averages, or other model inputs.
Assumptions: Estimates used where direct information is unavailable.
A report should identify the sources and limitations of its data.
PFAD Feedstock Eligibility in Biofuel Programs
Some regulatory or certification programs establish specific criteria for feedstocks used in biofuel production.
PFAD’s eligibility must be evaluated under the actual program.
Questions may include:
- How does the program define PFAD?
- Is it treated as a co-product, by-product, residue, or another category?
- Which chain-of-custody rules apply?
- What origin information is required?
- Are specific sustainability criteria applicable?
- Which greenhouse gas calculation method is required?
- Is independent verification necessary?
A favorable classification under one framework does not automatically apply elsewhere.
Avoiding Misleading Environmental Claims
Buyers and suppliers should avoid unsupported statements such as:
- “100% carbon neutral PFAD.”
- “Zero-emission feedstock.”
- “Guaranteed greenhouse gas savings.”
- “Automatically renewable-certified.”
- “Universally classified as waste.”
- “Deforestation-free without verification.”
Claims should be specific, supported, and limited to what the evidence establishes.
Product Carbon Footprint Review Checklist
- Identify the product and supplier.
- Define the assessment objective.
- Select the relevant standard.
- Establish the functional unit.
- Define the system boundary.
- Identify allocation requirements.
- Collect available primary data.
- Document secondary data sources.
- Calculate using the chosen method.
- Conduct uncertainty or sensitivity analysis where appropriate.
- Obtain required independent verification.
- Review proposed external claims.
Questions for Indonesian PFAD Suppliers
- Can the producing refinery be identified?
- Are batch or tank records available?
- What origin information is documented?
- Are relevant production data available?
- Is any carbon footprint report available?
- What methodology was used?
- Has the report been independently reviewed?
- Is a sustainability certification claimed?
- What is the certification scope?
- Can transaction-specific evidence be provided?
PFAD Carbon Documentation RFQ
Subject: Indonesian PFAD Supply and Carbon Accounting Documentation Inquiry
Buyer Company: [Name]
Country: [Country]
Product: Palm Fatty Acid Distillate
Quantity: [MT]
Industrial Application: [Details]
Required Sustainability Framework: [If Applicable]
Required LCA Methodology: [If Applicable]
System Boundary: [Details]
Functional Unit: [Details]
Origin Information Required: [Details]
Certification Requirement: [If Applicable]
Independent Verification Requirement: [Details]
Destination: [Country / Port]
Please identify potential suppliers and clarify which supporting data are available for independent evaluation.
Frequently Asked Questions
Does PFAD have a universal carbon footprint?
No. Results depend on the product system, methodology, and data.
Is PFAD automatically a zero-emission feedstock?
No.
Can a supplier provide a product carbon footprint?
Potentially, if a suitable assessment has been prepared.
Is an LCA the same as a COA?
No. A COA reports product analysis; an LCA assesses environmental impacts under a defined methodology.
Can PFAD be used in biofuel applications?
Potentially, subject to technical and regulatory suitability.
Does IEC guarantee greenhouse gas savings?
No. Any such claim requires a justified calculation and appropriate evidence.
Request PFAD Sourcing and Carbon Documentation Information
Evaluating Indonesian PFAD for a supply chain with greenhouse gas accounting or sustainability requirements?
Share your technical specifications and evidence requirements with IEC.
REQUEST PFAD SUPPLIER INFORMATION
IEC | INDONESIA EXPORT CENTER
Website: https://indonesiaexportcenter.com/
WhatsApp: +62 813-3302-277
Related Resources
PFAD Traceability and Sustainability Questions
PFAD Supplier Due Diligence Checklist
